Editorial independence: our scores and rankings are produced using the fixed criteria above and are not influenced by advertisers. This is an independent ranking site and is not operated by, or affiliated with, any provider we list.
Affiliate disclosure: some links on this page may earn us a commission at no extra cost to you. This does not affect our rankings.
| Best for | Not for |
|---|
| Criterion | Score | Note |
|---|---|---|
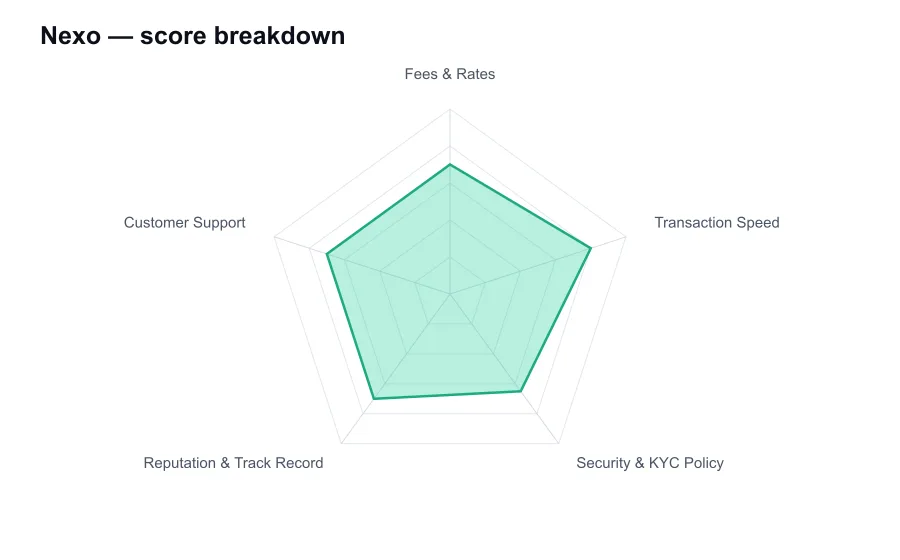
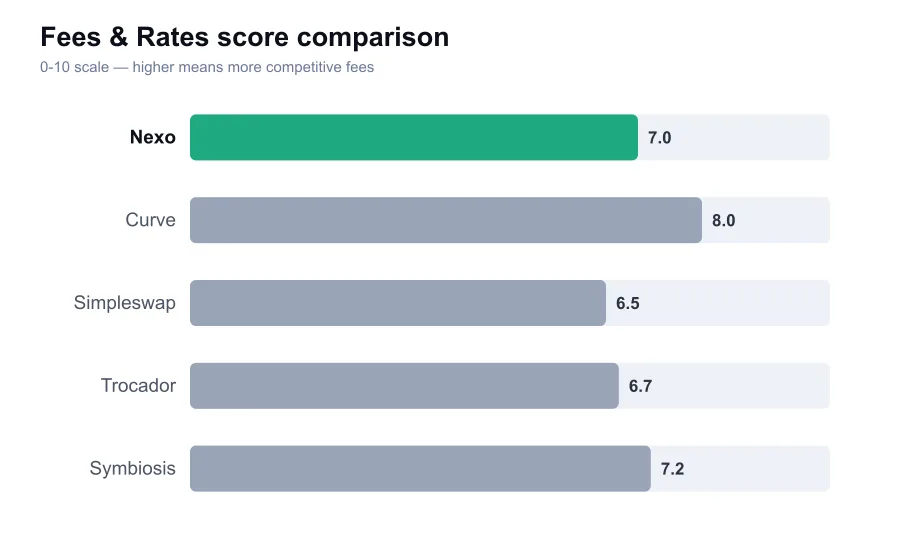
| Fees & Rates | 7.0 | Nexo Pro is competitive, retail swaps can carry spread |
| Transaction Speed | 8.0 | Fast internal swaps and generally efficient withdrawals |
| Security & KYC Policy | 6.5 | Strong controls, but lending adds material counterparty risk |
| Reputation & Track Record | 7.0 | Survived lender failures, with meaningful regulatory baggage |
| Customer Support | 7.0 | Useful chat access, uneven escalation for complex cases |
Nexo is a crypto financial platform rather than a conventional spot exchange. Its pitch is easy to understand: hold crypto, earn yield on selected assets, borrow against collateral, swap coins, and use a card tied to your portfolio. That package made Nexo one of the best known names in crypto lending. It also means users need to evaluate more than trading fees. They are taking platform, counterparty, and product risk every time they deposit.
The company launched in 2018 and built its reputation during the period when centralized lenders offered attractive yields on Bitcoin, Ether, and stablecoins. Some competitors, including Celsius, BlockFi, and Voyager, collapsed spectacularly. Nexo survived that era, and survival is meaningful. Still, the lesson from those failures is not that a surviving lender is risk free. It is that customers should be extremely selective about how much unsecured trust they place in any yield platform.
Nexo's exchange feature is convenient, but it is not the reason sophisticated traders choose the service. Standard retail swaps use a quoted conversion price, with costs reflected through spread and market conditions instead of a simple exchange commission that can be compared tick for tick with Binance or Coinbase Advanced. Nexo Pro is a separate, more trading focused venue and has used a maker and taker schedule that can be competitive at lower tiers, typically far below a retail swap spread.
For a quick conversion between major coins, the app is smooth. For recurring high volume trading, the standard exchange is not compelling. The quote may be reasonable in calm markets, but users should compare it against a liquid exchange before converting a substantial amount. Slippage and spread become more visible in thinner assets and during volatility. Nexo's polished screen should not make customers forget that convenience pricing is still pricing.
The earn product needs the most scrutiny. Advertised rates can depend on loyalty tier, asset, lockup choice, reward currency, jurisdiction, and the percentage of the account held in NEXO tokens. The highest advertised number is rarely the rate every customer receives. A stablecoin holder who must buy and retain a platform token to reach the top tier is taking additional token exposure, which can erase much of the extra yield if that token falls sharply.
Borrowing follows the same logic. Nexo lets clients use supported crypto as collateral and offers different loan to value levels depending on the asset. The convenience is obvious for someone who does not want to sell Bitcoin. But crypto collateral can fall violently, and an aggressive loan to value can produce margin calls or automatic collateral sales at the worst possible time. Borrowing against volatile crypto is not a low stress cash management tool.
Transfers into Nexo are generally as fast as the underlying network allows. Internal swaps execute quickly because they are ledger entries inside the platform. Withdrawals are usually processed on a schedule after security review, then wait for blockchain confirmations. Nexo has historically promoted free withdrawals, though eligibility and number of free withdrawals can depend on loyalty tier and program terms. Read the current conditions, particularly if you move smaller balances often.
The app and card experience are among Nexo's better qualities. The interface is clean, portfolio information is understandable, and the card makes the platform feel more like a financial account than a trading site. That is appealing, but it can encourage users to leave more assets on platform than they otherwise would. A seamless interface is not the same thing as deposit insurance, and crypto deposits are not protected like ordinary bank deposits.
Nexo uses mandatory identity verification for its core services. Customers should expect document checks, sanctions screening, and enhanced source of funds questions in some cases. This is not an anonymous exchange. The compliance approach has tightened as regulators have pushed centralized crypto firms into a more formal framework. Some users dislike that friction, but an institution offering lending and payment products without serious KYC would be a much greater concern.
Security features include two factor authentication, withdrawal controls, device and account security measures, and custody arrangements with institutional providers. Those are sensible defenses, yet the key risk is broader than a hacked password. Customers are exposed to Nexo's credit decisions, liquidity management, legal structure, and ability to honor withdrawals under market stress. Public attestations and explanations of collateral practices provide some comfort, but they are not a substitute for a full traditional bank style audit and regulator backed deposit guarantee.
Nexo's regulatory record is mixed. In the United States, the company reached a $45 million settlement with state regulators and the SEC in 2023 over its Earn Interest Product, and it stopped offering that product to US clients. That episode should not be minimized. It demonstrated that a product can look established and still run into serious regulatory barriers. The firm has also faced intense public scrutiny around its operations and legal positioning.
On the other hand, Nexo did not freeze withdrawals during the major lender failures, and it has continued operating internationally. That gives it a stronger track record than many failed yield platforms. It should not be placed in the same mental category as a bank, however. The correct comparison is a surviving, centralized crypto lender with a broad product menu, not a protected savings institution.
Customer support is reasonably accessible through in app and web channels, including live chat for many issues. Basic questions are usually handled quickly. The harder cases involve compliance documents, liquidations, account restrictions, or transfers held for review. Those are the moments that define a financial platform, and public reports show uneven experiences. A user with a complex issue may find that polished front line support gives way to slow escalation.
Nexo is best for an experienced crypto holder who understands collateral risk, does not need immediate access to every deposited coin, and wants an integrated lending and card platform. It is a poor fit for anyone treating yield as guaranteed income or keeping emergency savings in stablecoins because the rate looks attractive. The platform's quality is real. So is the risk premium embedded in every product that promises more than simple self custody.
My view is that Nexo is one of the more capable survivors in centralized crypto finance, but surviving a crisis is not a blank check. Its app, card, lending tools, and broad asset support are better than those of many retail exchanges. Its weak spot is inherent, not cosmetic: customers must trust a private company with assets and credit risk. Use Nexo for a deliberate allocation, keep your most important long term holdings outside it, and never borrow against crypto without a plan for a severe market drop.
| Pros | Cons |
|---|
Nexo fits experienced holders who want to borrow against crypto or use a portfolio linked card without managing several apps. It can also suit traders who specifically use Nexo Pro and understand custody risk. It does not fit conservative savers, US users seeking Earn products, or anyone who needs bank like protection. Self custody is the better home for core long term holdings.
It has meaningful security controls, but it is custodial and exposes users to company and lending risk. A hardware wallet is safer for core holdings.
Retail swaps use quoted pricing that can include spread. Nexo Pro uses a separate maker and taker fee schedule that is easier to compare.
Nexo stopped offering its Earn Interest Product to US clients following its 2023 regulatory settlement.
You pledge supported crypto as collateral. If collateral value falls too far relative to the loan, additional collateral or automatic repayment can be required.
| Alternative | Score |
|---|---|
| Curve Review | 7.1/10 |
| Simpleswap Review | 7.0/10 |
| Trocador Review | 7.0/10 |
| Ripio Review | 7.2/10 |
| Symbiosis Review | 7.2/10 |
| ChangeNow Review | 7.2/10 |